Intercompany reconciliation in S/4HANA: why it breaks
Intercompany reconciliation fails on master data drift and exchange rate timing, not accounting skill: the same invoice booked from two sides never matches when trading partners, profit centers and valuation dates diverge. The fix is structural: enforce trading partner and partner profit center at entry, automate clearing with F.13E, and use ICMR for real-time matching from the Universal Journal. Teams that split reconciliation cases by dimension and protect the close with period-locked statements cut reconciliation from weeks to days.
Here is a sentence that has cost more month-end weekends than any technical bug I know: "the same intercompany invoice was booked on both sides, so why doesn't it match?" It does not match because profit centers, trading partners, and valuation dates diverge between the two company codes before anyone touches a keyboard. Intercompany reconciliation is not an accounting skill problem. It is a master data and exchange rate timing problem, wearing an accounting costume.
That distinction matters, because teams keep trying to fix it with better accountants and more overtime. The accountants are fine. The documents were never coded consistently at entry, and no amount of reconciliation effort can pair records that were born incompatible. The fix is structural: enforce the master data at entry, automate the clearing, and let the system do the matching it was built for.
Why intercompany is structurally hard
Start with the asymmetry that defines the problem. An intercompany transaction is internal, it is not real revenue or expense, yet a record taken by one party must be matched by the other with the same accuracy as any external transaction. Company A books a sale to Company B. Company B books a purchase from Company A. Same economic event, two sets of records, two points of view, and the matching has to survive time differences, currency differences, and whatever communication channel the two teams use.
Walk one invoice through it and you see the geometry. Company A ships goods, books revenue, and posts to its receivables, with its own profit center, its own currency, its own posting date. Company B receives the goods, books inventory, and posts to its payables, with a different profit center, possibly a different currency, possibly a different date, and the trading partner field filled in from memory or not at all. The accountants on both sides are competent. The records simply do not share enough fields to find each other. Every reconciliation failure I have investigated in a cutover traces back to that geometry: the two sides were never coded to meet.
At group scale that manual matching is what drags the close to one or two weeks. Accountants match AP in one company against AR in another, transaction by transaction, usually in spreadsheets, usually at month end, under deadline. The effort is real, the audit trail is weak, and the status is unknowable until someone asks the person doing the work.
The paradox is that this is the most painful process in the close and, until recently, one of the least automated. Every ERP team knows the pain; very few have a systematic answer.
The two real causes: master data drift and FX timing
Let me be specific about what actually breaks, because the failure modes tell you where the fix lives.
Master data drift: the quiet killer
Master data drift is the quiet killer. The trading partner lives in field VBUND of the business partner master, and if it is missing or inconsistent between the two sides, the documents can never be paired, no matter how carefully they are booked. The same applies to profit center and partner profit center: if company A posts to profit center P100 while company B posts the mirror entry to P200, the match fails on a field that was supposed to be identical. This is not a posting error; it is a master data error that no posting skill can repair. SAP treats it as serious enough to make trading partner mandatory for the classic intercompany reconciliation process 002, and the discipline should not stop there.
Exchange rate timing: variance, not error
Exchange rate timing is the second cause, and it is the one that confuses people most. Intercompany balances between two company codes are not equal when currency conversion uses rates that vary by posting date or by valuation policy. The same intercompany invoice, translated at the posting date in one company and at period end in another, legitimately produces two different numbers. Those differences are variance, not error. The books are not wrong; the translation happened at different moments under different rules. The fix is tolerance-based matching plus systematic adjustment postings, not a hunt for the accountant who "made a mistake."
Organizational design and ownership
There is a third, structural cause that usually predates everything else: organizational design. Multiple controlling areas force master data duplication and workarounds for cross-company allocations, and every duplication is another place the two sides can drift apart. One global healthcare group that left intercompany to the sales stream lost about six months to redesign. An automotive OEM that ran a dedicated intercompany workstream treated it as a success factor. The architecture decides how hard your reconciliation will be, before configuration starts.
Ownership is part of that architecture, and it is the part teams argue about last. Intercompany reconciliation that belongs to nobody until month end belongs to whoever is loudest at month end, which is the wrong owner. The groups that reconcile in days have a named owner for the intercompany process, a documented physical versus ownership versus invoice flow, and a standing workstream rather than a fire drill. Whether that owner sits in a shared service center or in each entity is a structure choice; that the owner exists is not optional.
The tool that changes the math: ICMR
Since 1909 on-premise and 1908 in the cloud, S/4HANA ships Intercompany Matching and Reconciliation, ICMR, built into the core. Its defining property: it matches transactions in real time straight from the Universal Journal, with no ETL, no extracts, no staging layer. ACDOCA is the source, and the matching runs continuously instead of at month end. That single change moves finance teams from reactive investigation to continuous monitoring.
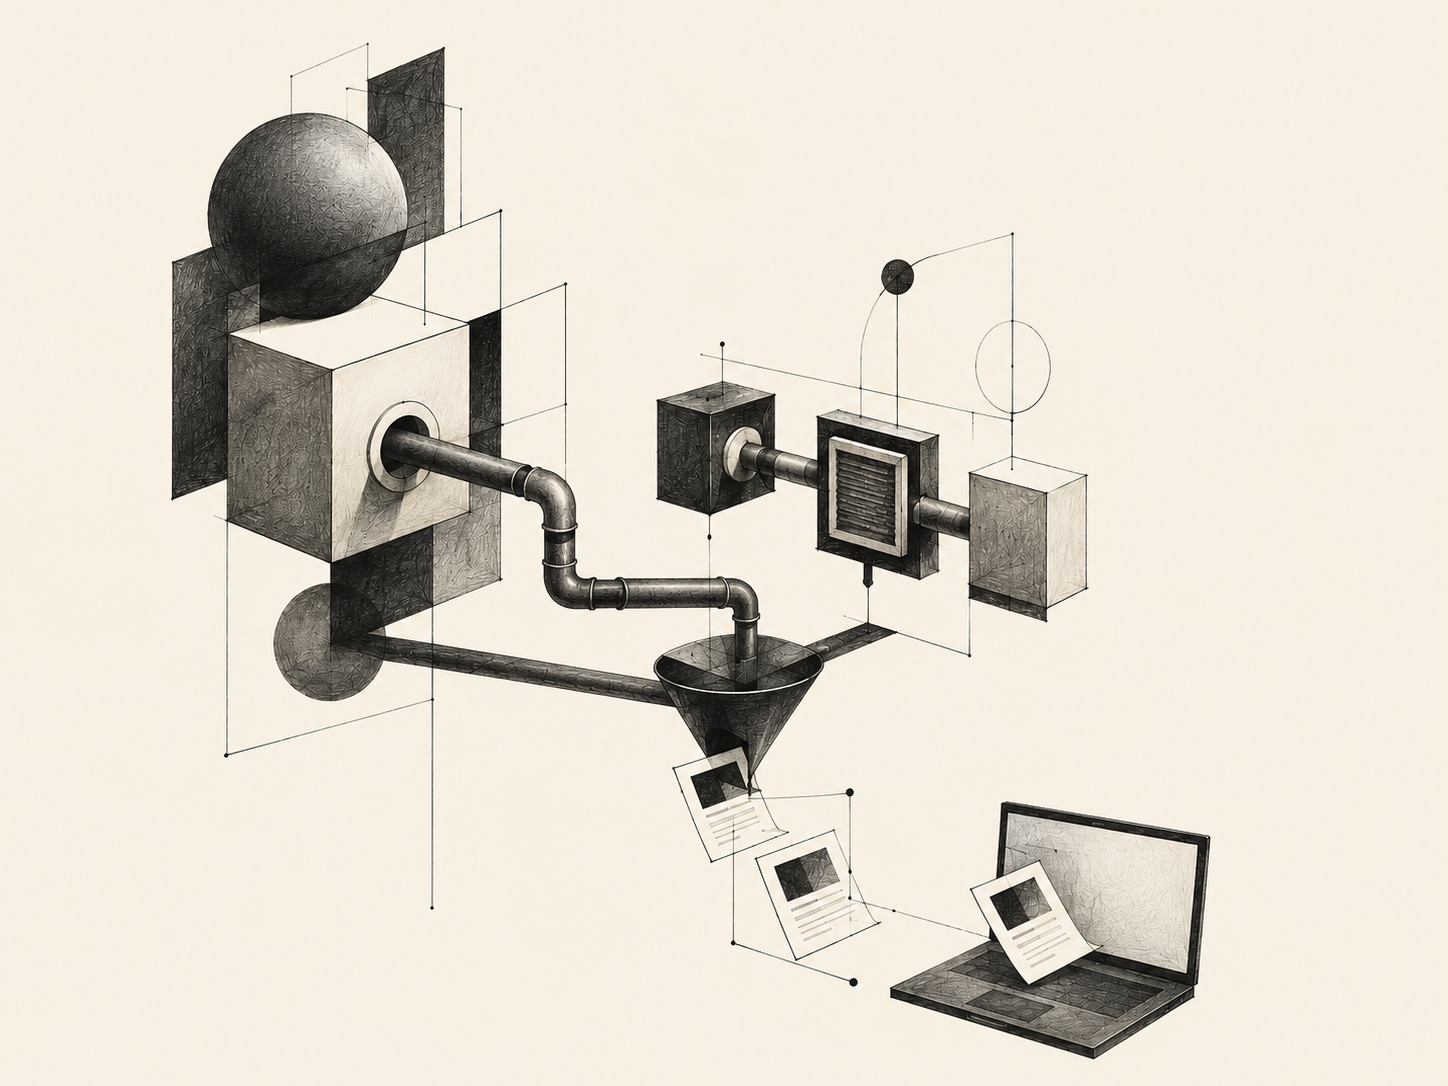 From system to report — data flowing directly from the accounting journal into reconciliation statements, no staging layer
The four-step loop
The process is a clean four-step loop: collect data, match documents, solve discrepancies, check reconciliation balances. Three modules cover the ground: Matching at transaction level, Reconciliation at aggregation level, and Automatic Posting for variance correction, accruals, and eliminations. Since 1909 the standard scope item 40Y delivers the data sources, matching methods, and reconciliation cases out of the box, and the SAP notes 2818187 and 2815304 carry the sample methods and the practical FAQ.
The data side
The data side is more open than people expect. ICMR reads ACDOCA, the accounting journal, ACDOCU, the consolidation journal, or the classic BKPF and BSEG, and non-SAP data can be uploaded or replicated into the same matching run. That matters for groups with subsidiaries outside the ERP: the subsidiary's ERP extract lands in the same reconciliation engine as the S/4HANA postings, which is how a group reconciles a mixed landscape instead of rebuilding it in Excel.
The matching model
The matching and reconciliation model is built on the organizational dimensions you already fight with: company and partner company via the trading partner, profit center and partner profit center, and consolidation unit for group reporting. That means you can split the problem along the axes where your discrepancies actually live, instead of reconciling everything against everything. One practical rule from real implementations: balance sheet accounts and P&L accounts need different data sources, because they run on different fiscal year period settings. Fold them into one source and you inherit a mismatch you did not create.
Operational setup
The operational side is worth knowing before you build anything custom. The PFCG role SAP_BR_RECON_ACCOUNTANT bundles the Fiori apps: Maintain Data Source, Define Matching Method, Define Reconciliation Cases, Manage Assignments, Reconciliation Status Overview, Manage Reconciliation Close, and Simulate Elimination. If you are on 1909 or later, the question is not "which tool do we buy"; it is "how fast can we configure the native one." Do not rebuild spreadsheets on top of a system that now matches in real time; that is paying twice for the same work.
For landscapes that predate 1909, or P&L heavy processes that do not use open item management, the classic ICR processes still apply: process 001 for GL open items, process 002 for GL accounts without open item management, process 003 for customer and vendor open items. Clearing runs through F.13E, automatic clearing with currency, which clears open items including FX differences. The difference postings use KDM for revaluation differences and KBS for balance sheet translation differences, and routing them through the system instead of hand posting them is what keeps the audit trail coherent.
Enforce at entry, automate the clearing
The structural fix has three layers, and they go in this order.
 Finding the path — a red thread leading through the maze
Layer one: master data mandatory at entry
First, make the master data mandatory at document entry. Trading partner, partner profit center, and consistent intercompany control keys are not nice-to-have fields; they are the conditions that make automatic matching possible. If you can book an intercompany document without a trading partner, your system is configured to create unreconcilable records, and you will reconcile them by hand forever. Close that hole in the validation logic before you invest in any matching tool.
Layer two: reconciliation cases by dimension
Second, define reconciliation cases by dimension and split them deliberately. Company-code pairs for AR against AP. Profit center pairs for intercompany sales against cost. Consolidation unit dimension for group reporting. Separate data sources for balance sheet and P&L. Access control per case, so the AR team sees AR views and the AP team sees AP views. The granularity of your cases is the granularity of your monitoring; a single catch-all case is a single catch-all blind spot.
Layer three: automate the clearing
Third, automate the clearing and protect the close. Match, do not chase. Define matching tolerances for FX derived differences, group or store rate driven differences, create adjustment entries on demand, and clear through F.13E so revaluation differences post via KDM and KBS systematically. Then activate the reconciliation close process with Period Initially Closed, so current period matching can never rewrite prior period statements. Pair-level locks let you close one pair without freezing the whole group, which is the difference between a controlled close and a group-wide freeze every month. The close improvements in recent releases also add snapshot reconciliation statements and elimination control, so the statement the auditors see is the statement that was true at close, not whatever the system shows weeks later.
For teams that want to push further, the Intelligent Intercompany Reconciliation option adds ML-based matching on top of ICMR, with its own training, monitoring, and inference apps. Treat it as an accelerator on a clean base: it learns from matched pairs, which means its quality is capped by the quality of the data source setup and the master data underneath. If the base is messy, the model learns the mess.
What to expect from a cutover
If you are migrating, treat intercompany as a first-class workstream from day one, because cutovers are where IC mismatches are born. The partner fields, the profit centers, and the open items must be migrated consistently on both sides of every pair. I have fixed real IC mismatches in cutovers where company A's open items came across with trading partners and company B's arrived without them; the first reconciliation run after go-live found hundreds of orphans, and the team spent a week explaining a problem that was created by a migration rule, not by the business.
A few expectations to set with the project team. ICMR is a tool, not a fix: it surfaces mismatches in real time, but it requires data source setup, matching method definition, and master data quality to do it. Upgrading enables, it does not eliminate. And if your group is small, with a handful of intercompany transactions a month, spreadsheets are a pragmatic stopgap; the threshold where they stop being pragmatic is exactly where the manual close starts taking days, and you will feel it before you measure it. There is no virtue in tooling up a problem you do not have.
The other expectation is about FX. Intercompany balances legitimately differ after translation at different rate dates and valuation policies. When you see a difference, ask which rate rule produced it before asking which accountant made a mistake. Most "unexplained" IC differences are explained by the valuation policy the moment someone looks.
The close that results
Get the structure right and the reconciliation stops being an event. The matching runs continuously, the exceptions surface in the Reconciliation Status Overview while there is time to solve them, the pair-level locks keep the close moving, and the elimination simulation shows you the group view before you commit. Month end becomes a verification of what you already know, instead of a discovery of what you did not.
That is the outcome worth aiming for, and it is available in the product you already own. The work is not in the tooling; it is in the discipline of entering the master data once, correctly, on both sides, and letting the system do the matching it was designed for. Intercompany reconciliation is hard until you stop treating it as an accounting exercise and start treating it as a data structure problem. The structure is fixable. The overtime is optional.
Sources
- Intercompany Matching and Reconciliation (ICMR)
- Handling of Exchange Rate Differences
- S/4HANA Inter Company Reconciliation Process GL accounts 002
- How to define intercompany reconciliation cases
- Intercompany Reconciliation (Customer/Vendor: Process 003)
- Intercompany Reconciliation Close Improvements
- Automating Intercompany Reconciliation in SAP S/4HANA: Best Practices for Financial Transparency
- Intercompany in SAP S/4HANA: Why Is It So Hard and How Do You Design It Right?
- Intercompany Matching and Reconciliation (ICMR)
- Understanding Intercompany Matching and Reconciliation with SAP S/4HANA
- F13E Automatic Clearing With Currency
- Managing Exchange Rate Differences
Frequently asked
Why don't intercompany balances match in SAP?
Because the two sides were coded differently at entry: missing or inconsistent trading partner (VBUND), profit center mismatches, and exchange rates applied at different dates or valuation policies.
What is ICMR in S/4HANA?
Intercompany Matching and Reconciliation, built into S/4HANA since 1909 (on-premise) and 1908 (cloud). It matches transactions in real time from the Universal Journal with no ETL.
How do you fix intercompany reconciliation?
Make trading partner and partner profit center mandatory at entry, define reconciliation cases by dimension, match with FX tolerances instead of chasing cents, clear with F.13E, and activate period-close locks.
Need this in your organisation?
I work with a small number of clients each quarter on ERP strategy and IT-department automation. If the questions raised above are live in your team, get in touch.
Start a conversation →